TL;DR
- Supply Squeeze: Memory maker Micron expects shortages to worsen in 2027 and 2028, raising supply concerns for data-center and device manufacturers.
- AI Memory: Most of its 2027 high-bandwidth memory for AI chips is contracted at significantly higher prices than in 2026.
- Factory Ramps: New chip factories need several quarters after first output to add meaningful supply.
- Record Revenue: Fiscal 2026 fourth-quarter revenue reached $54.23 billion, up 379% from a year earlier.
Micron expects memory shortages to deepen through 2028 because growing AI demand is absorbing capacity faster than new factories can add it. For data-center operators and device makers, the chipmaker’s September 30, 2026 earnings update points to tighter competition for supply even as industry shipments increase.
Chief Executive Sanjay Mehrotra expects demand to exceed supply in both 2027 and 2028, with no clear date for a return to balance. Micron’s fiscal 2026 fourth-quarter results, covering the period ended September 3, put quarterly revenue at $54.23 billion, against $11.32 billion a year earlier.
AI Demand Strains Memory and Storage
AI systems need several kinds of memory and storage. Dynamic random-access memory, or DRAM, holds the active data processors use. High-bandwidth memory, or HBM, is a specialized form of DRAM that gives AI accelerators rapid access to data close to the processor. NAND flash retains data in solid-state drives, or SSDs, which feed those systems with datasets and stored model information.
Larger AI models, longer conversations and more simultaneous requests increase requirements across that hierarchy, according to Micron. The pressure therefore reaches ordinary server working memory and storage as well as the stacked memory beside AI chips. Data-center SSD revenue approached $10 billion in the quarter, more than ten times the year-earlier level and over two-thirds of Micron’s total NAND revenue. Micron sees additional storage demand from moving AI context data into SSDs and replacing hard drives.
Making more HBM also consumes manufacturing capacity that could otherwise support conventional DRAM. Mehrotra’s earnings-call explanation links newer HBM generations’ greater silicon requirements with smaller productivity gains from future manufacturing processes. More investment and more advanced production technology can add output, but the company expects demand to absorb those gains.
Memory makers were already shifting production toward HBM in March. Micron’s September outlook still anticipates industry DRAM bit shipments growing in the low-20s percentage range annually in 2027 and 2028, and NAND shipments in the mid-20s. Its shortage forecast rests on demand growing faster than that expanding supply.
New Factories Take Time to Add Supply
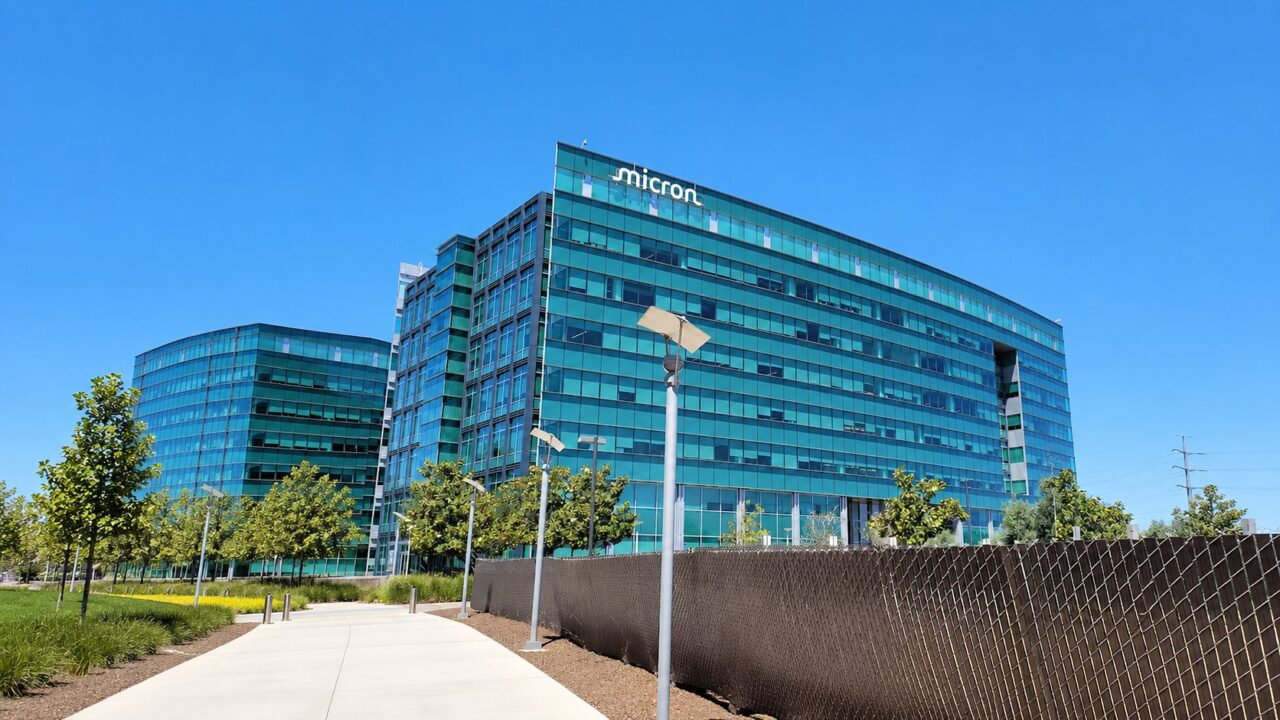
Micron’s Idaho ID1 plant is expected to produce its first wafers, thin slices of silicon on which chips are made, in mid-2027. Production at new DRAM and NAND factories then ramps gradually, becoming a meaningful source of supply a few quarters after first output. Micron President and Chief Operating Officer Manish Bhatia described that delay in an interview with Reuters.
HBM packaging stacks and connects memory chips into memory devices for AI accelerators. Micron’s Singapore facility is expected to add this packaging capacity in early 2027. In Taiwan, Micron expects meaningful product shipments from its Tongluo plant in mid-2027.
Micron’s planned production additions, as of September 30, 2026
Chief Financial Officer Mark Murphy forecast approximately $25 billion in capital spending in the first half of fiscal 2027, including around $11.5 billion in the first quarter, with higher spending in the second half. Those amounts are net of anticipated government incentives. Most of the increase over earlier spending plans goes toward construction, principally to bring additional manufacturing space forward into late 2028 and beyond.
New plants and equipment improvements provide real additional supply. Micron is also optimizing existing manufacturing space, and customers are moderating growth in memory per server so they can ship more machines. The company nevertheless expects server unit shipments to grow in the high teens in both 2026 and 2027.
Higher Prices Lift Supplier Profits
Micron’s quarter shows how constrained supply is translating into higher realized prices. DRAM bit shipments increased in the mid-single digits from the previous quarter, while average selling prices rose in the high teens. NAND bit shipments increased about 10%, while average selling prices rose about 30%. Revenue growth outstripped volume growth in both categories.
For fiscal 2026, Micron reported $133.19 billion in revenue and $84.97 billion in net income under standard U.S. accounting rules, or GAAP.
Gross margin, the share of sales left after direct production costs, reached 83% in the Cloud Memory business, compared with 59% a year earlier. The Core Data Center business reached 90%, against 41%. The Cloud Memory margin was flat from the preceding quarter because a larger HBM share offset higher prices. Micron expects its significantly higher contracted HBM prices for 2027 to narrow the profitability gap with conventional DRAM.
Agreements cover the vast majority of Micron’s calendar-2027 HBM bit supply at significantly higher prices than in 2026. Separately, Mehrotra said more than 75% of all 2027 output was already committed across customers with and without long-term strategic agreements.
The company forecasts first-quarter fiscal-2027 revenue of $61.5 billion, plus or minus $1.5 billion. Bob O’Donnell, chief analyst at TECHnalysis Research, interpreted the earnings and forecast as evidence that AI infrastructure spending remains resilient.
Customers Commit to Secure Supply
Micron has signed 26 multiyear strategic customer agreements, up from 16 in June. They are take-or-pay contracts: customers commit to purchasing specified volumes or paying for them. Micron describes the return as supply assurance and closer coordination on future products. The committed demand gives the company greater confidence to fund factories with long construction lead times.
The agreements are estimated to cover more than 35% of Micron’s revenue through 2030, with some extending into 2031. Three-quarters of that expected contract revenue has a defined pricing framework. Most of that share has price bands with floor and ceiling prices. The remaining quarter is priced periodically against market conditions. Customers therefore receive different forms of price visibility along with their supply commitments.
In December 2025, Micron announced plans to exit the Crucial consumer business, which sold branded memory and storage directly through retail channels. Chief Business Officer Sumit Sadana said the decision would improve supply and support for larger strategic customers in faster-growing markets amid AI-driven data-center demand.
Device manufacturers remain part of Micron’s business, but their outlook differs from that of server customers. Micron expects premium PCs and smartphones to support industry revenue growth in 2026 despite possible double-digit declines in overall unit sales. Its own Mobile and Client business increased quarterly revenue 14% from the preceding quarter even as shipped bits fell, driven by higher prices.